

 Facebook
 X
 Pinterest
 Copy Link
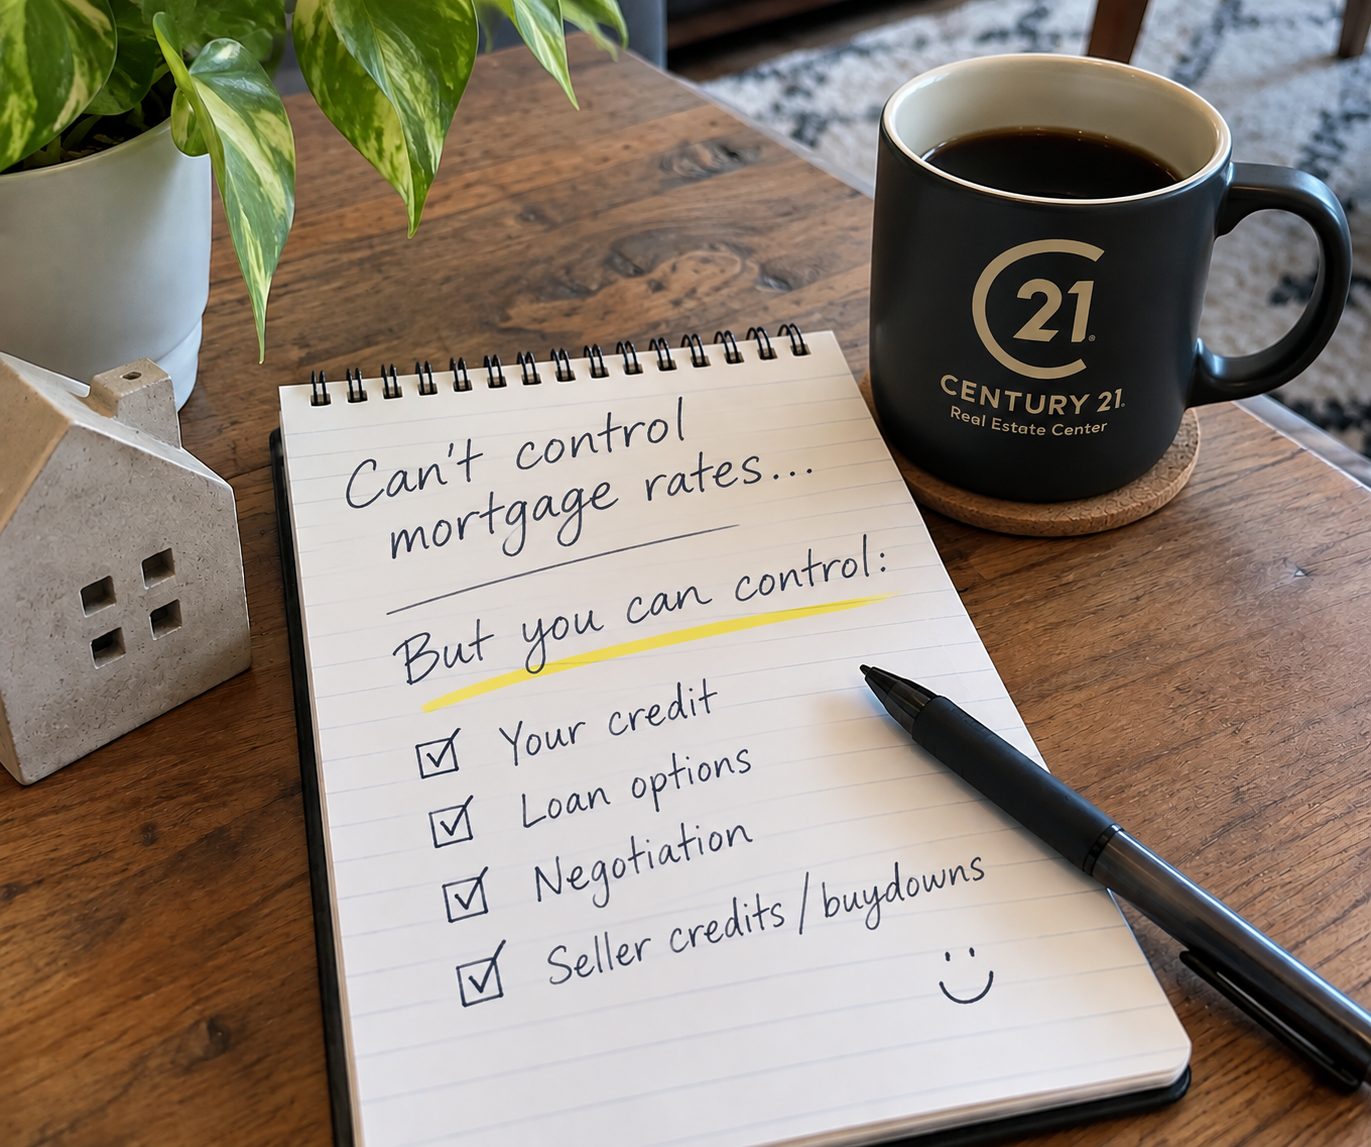
If I had a dollar for every time a buyer told me, “I’m just going to wait for rates to come down,” I could probably buy down somebody’s interest rate myself.
I get it.
Mortgage rates have been one of the biggest frustrations for homebuyers over the past few years. And lately, they’ve been moving in the wrong direction again.
But here’s the problem with waiting for the “right” mortgage rate:
None of us gets to decide what that rate is going to be.
Mortgage rates are influenced by inflation, economic data, global events, Federal Reserve policy, bond markets and a whole list of things completely outside your control.
What you CAN control is how you approach buying a home.
And in today’s market around South Snohomish County and North King County, buyers may have more options than they realize.
Your Credit Still Matters
This is probably the least exciting part of this conversation, but it matters.
Generally, the stronger your credit profile, the better the loan terms available to you. If buying a home is even six months away, talking with a good lender early can be worthwhile.
You may discover that your credit is already where it needs to be. Or you may find that a few relatively small changes could put you in a better position when it’s time to buy.
Either way, finding out before you’re standing in a house you love is a whole lot better than finding out afterward.
Don’t Assume Every Loan Looks the Same
There isn’t one universal mortgage rate.
Conventional, FHA, VA and USDA loans can have different rates, costs and qualification requirements. Loan terms matter. Down payment matters. Your financial situation matters.
Even two lenders looking at the same buyer may structure the financing differently.
This is why I’m a big believer in getting an actual loan scenario instead of using whatever mortgage calculator pops up next to a listing online.
But there’s another piece of this that I think is particularly important in our current market.
The Seller May Be Able To Help
This is where things have changed.
A few years ago, when sellers were receiving multiple offers within days or even hours, asking them to contribute toward a buyer’s closing costs or interest rate was often a quick way to get your offer moved to the bottom of the pile.
That isn’t necessarily the market we’re in today.
Some homes are still selling quickly. Others are sitting.
And when a seller has been on the market for a while, price isn’t the only thing we can potentially negotiate.
Depending on the transaction and loan program, we may be able to negotiate a seller credit that a buyer can use toward closing costs or an interest rate buydown.
For the right buyer, reducing the monthly payment may be more valuable than negotiating the exact same amount off the purchase price.
That’s why I don’t like looking at the list price, mortgage rate and monthly payment as three completely separate things. They’re all part of the same negotiation.
New Construction Has Entered This Conversation Too
Builders know buyers are sensitive to monthly payments.
That’s why we’re seeing builders around the country use financing incentives, closing cost credits and rate buydowns to attract buyers. Recent national data has shown buyers of newly built homes getting lower average mortgage rates than buyers purchasing existing homes, largely because of these incentives.
That doesn’t automatically make new construction the better choice.
But if we’re comparing homes, I want to know what the builder is offering. Sometimes the advertised purchase price doesn’t tell the whole story.
The same is true with resale.
A motivated resale seller may have room to negotiate that isn’t obvious from the listing.
And Don’t Get So Focused on the Rate That You Forget the Price
This one is important.
Let’s say you wait because you want a substantially lower mortgage rate.
Maybe rates eventually fall. Maybe they don’t. Nobody knows exactly what happens next.
But what happens to home prices while you wait? What happens to inventory? What happens to buyer competition if rates fall enough to bring a large group of buyers back into the market?
There’s another way to look at it.
If today’s market gives you an opportunity to negotiate $20,000 or $30,000 off the price of a home, or negotiate significant seller credits, that has real value too.
A mortgage may potentially be refinanced later if rates and your circumstances make it worthwhile.
You cannot refinance the price you paid for the house.
That doesn’t mean everyone should rush out and buy a home because rates might change. It means the mortgage rate shouldn’t be the only number driving the decision.
Stop Waiting for the Perfect Number
If you’re hoping I’m going to predict where mortgage rates will be six months from now, I’m going to disappoint you.
I don’t know.
Neither does anyone else.
What we CAN do is look at the market we have today.
What can we negotiate on the home?
Would the seller consider contributing toward your closing costs?
Could we use a credit toward a temporary or permanent rate buydown?
Is there a different loan structure that makes more sense?
Is a builder offering an incentive worth considering?
And most importantly, does the purchase make financial sense for you at the numbers we can actually get today?
That’s a much better conversation than trying to guess what mortgage rates are going to do next.
If you’re considering buying in South Snohomish County or North King County, let’s run the numbers on a few real homes and see what the opportunities actually look like. You may have more control over that monthly payment than you think.

